How the Loan Eligibility Calculator Works
Lenders use a ratio called FOIR — Fixed Obligation to Income Ratio — to decide how much of your income can go toward loan repayments. Most set it between 40% and 55%, with higher limits for higher earners.
Enter your monthly income, then the total of your existing EMIs — car loan, personal loan, credit card minimums, anything with a fixed monthly obligation.
The calculator works out the EMI you have room for, then converts that into a loan amount at the interest rate and tenure you expect.
The relationship runs backwards from a normal EMI calculation: instead of finding the EMI for a loan, it finds the loan that fits a given EMI.
Try adjusting the tenure. A longer tenure raises the amount you're eligible for, because the same EMI stretches further — though it costs considerably more in total interest.
Benefits of Using a Loan Eligibility Calculator
- Know your ceiling before you apply: avoid a rejected application (which can dent your credit score) by checking your realistic borrowing limit first.
- Plan around existing EMIs: see exactly how much your current loans and card balances are eating into your eligibility.
- Test tenure trade-offs: check how stretching the tenure raises your eligible amount, and weigh that against the extra total interest.
- Set a smarter borrowing target: use the ceiling as a reference point, then decide how much less than that you actually want to borrow.
- Free and instant: get an estimate without a credit check or submitting any documents to a lender.
Formula Used
The EMI you can support is converted into a loan amount using the present value of an annuity:
Eligible Loan = EMI × ((1+r)^n − 1) / (r × (1+r)^n)- EMI(Monthly income × FOIR%) − existing EMIs
- rMonthly interest rate (annual rate ÷ 12 ÷ 100)
- nTotal number of monthly instalments (tenure in years × 12)
Example Calculation
Suppose you earn 1,00,000 a month, already pay 10,000 in EMIs, and the lender applies a 50% FOIR on a 20-year loan at 9%.
- Monthly Income100,000
- Existing EMIs10,000
- FOIR50%
- Interest Rate9% p.a.
- Tenure20 years
- EMI available ≈ 40,000 · Eligible loan amount ≈ 44,45,800
Important Assumptions
- This is the income-based ceiling only. Lenders also weigh your credit score, age, job stability, employer category and repayment history, any of which can reduce the sanctioned amount.
- For secured loans there is a second, separate ceiling. Home loans are also capped by the loan-to-value ratio on the property, so the sanctioned amount is the lower of the two limits.
- Use your net take-home pay, not your CTC, for the income figure. Lenders assess what actually reaches your account.
- FOIR limits vary by lender and by income band. If you don't know the lender's figure, 50% is a reasonable starting assumption.
- Stable additional income — rental income, or a co-applicant's salary — can raise the figure. Variable income like bonuses is usually discounted or ignored.
Frequently Asked Questions
Guides & Articles
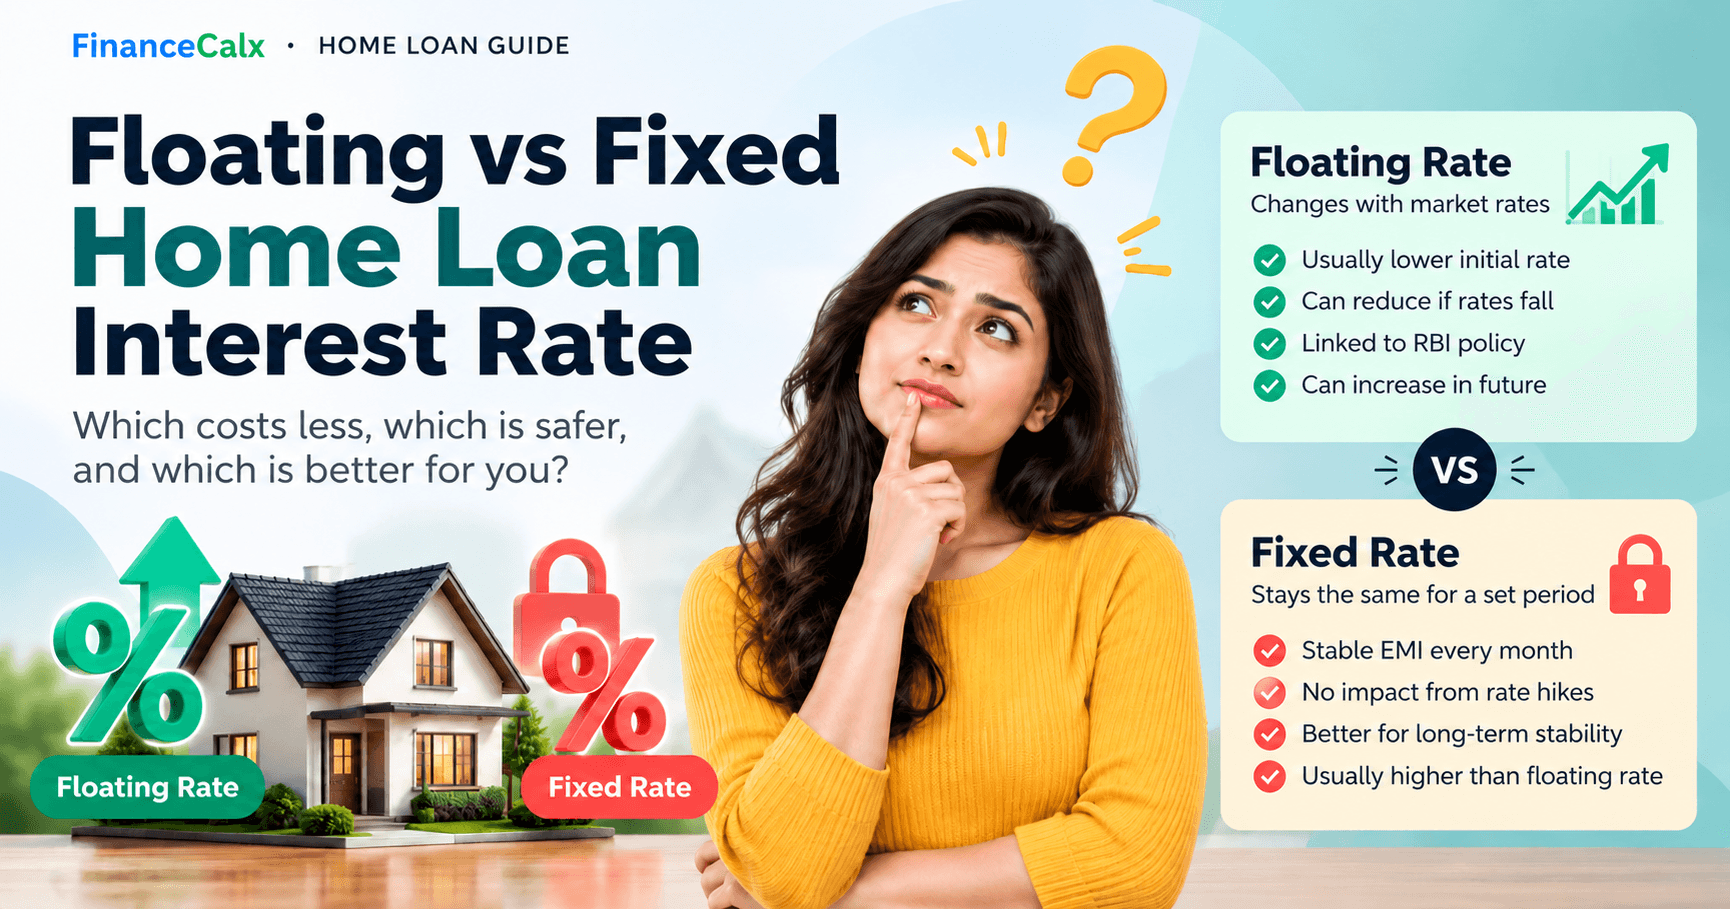
Floating vs Fixed Home Loan Interest Rate: Which Is Better?
On a ₹50 lakh, 20-year home loan, a 9.5% fixed rate costs ₹7.72 lakh more interest than an 8.5% floating rate that never changes. Here is when fixed still wins, what a rate rise does to your EMI, and how to choose.