How the NPS Calculator Works
Enter your current age, planned retirement age, monthly contribution, and the expected annual return on your NPS investments — this depends on your chosen mix of equity, corporate debt and government bond funds.
The calculator projects your monthly contributions forward using compound growth to estimate your total corpus at retirement, clearly separating your own contributions from the estimated investment growth.
At retirement, current NPS rules require you to use at least 40% of the corpus to buy an annuity (a regular pension); the rest can typically be withdrawn as a lump sum. Adjust the annuity percentage and assumed annuity rate to see the effect on your estimated monthly pension.
Benefits of Investing in NPS
- Extra tax deduction beyond 80C: under the old tax regime, NPS offers an additional deduction of up to ₹50,000 under Section 80CCD(1B) — now Section 124(3) of the Income Tax Act, 2025 — over and above the ₹1.5 lakh limit under Section 80C, a benefit most other retirement products don't offer.
- Low fund management costs: NPS has some of the lowest expense ratios among market-linked retirement products, so a larger share of your returns stays invested rather than going toward fees.
- Choice of asset allocation: you can choose your own mix of equity, corporate debt and government bond funds (or opt for an auto-allocation model that shifts to safer assets as you near retirement), letting you match the risk to your comfort level.
- Portability: your NPS account and PRAN (Permanent Retirement Account Number) stay with you across jobs, cities and even changes in employment sector, so there's no need to close or transfer anything.
- Disciplined, long-term retirement savings: withdrawal restrictions before retirement encourage the corpus to stay invested and compound over decades, rather than being dipped into for short-term needs.
Formula Used
Each month, the corpus grows as your contribution is added and compounded:
Corpus = (Corpus + Monthly Contribution) × (1 + r/12), repeated monthly- rExpected annual return (as a decimal)
- Annuity CorpusCorpus × Annuity %
- Monthly Pension (est.)(Annuity Corpus × Assumed Annuity Rate) ÷ 12
Example Calculation
A 30-year-old contributing to NPS until age 60.
- Current Age30
- Retirement Age60
- Monthly Contribution₹5,000
- Expected Return10% p.a.
- Estimated Corpus ≈ ₹1.14 crore (Contributions ≈ ₹18,00,000, Growth ≈ ₹96 lakh)
Important Assumptions
- Returns on NPS are market-linked and not guaranteed. The expected return you enter is an assumption, not a promise of actual performance, and will vary based on your chosen fund mix and market conditions.
- This calculator assumes a constant monthly contribution and constant expected return throughout the investment period, which real-world contributions and markets rarely follow exactly.
- This calculator assumes the expected return rate compounds monthly at a nominal rate (annual rate ÷ 12), consistent with how most mutual fund and SIP-style calculators compute returns. Some calculators instead use the true effective annual compounding rate, which shows a slightly lower projected corpus for the same inputs.
- Current NPS rules require a minimum annuitization of 40% of the corpus at retirement (this can vary with corpus size and withdrawal rules, which can change). The estimated monthly pension also depends on the annuity rate offered by the insurance provider at the time, which isn't guaranteed.
- This calculator doesn't account for NPS-related tax benefits, fund management charges, or partial withdrawal rules — all of which can affect your actual outcome.
Frequently Asked Questions
Guides & Articles
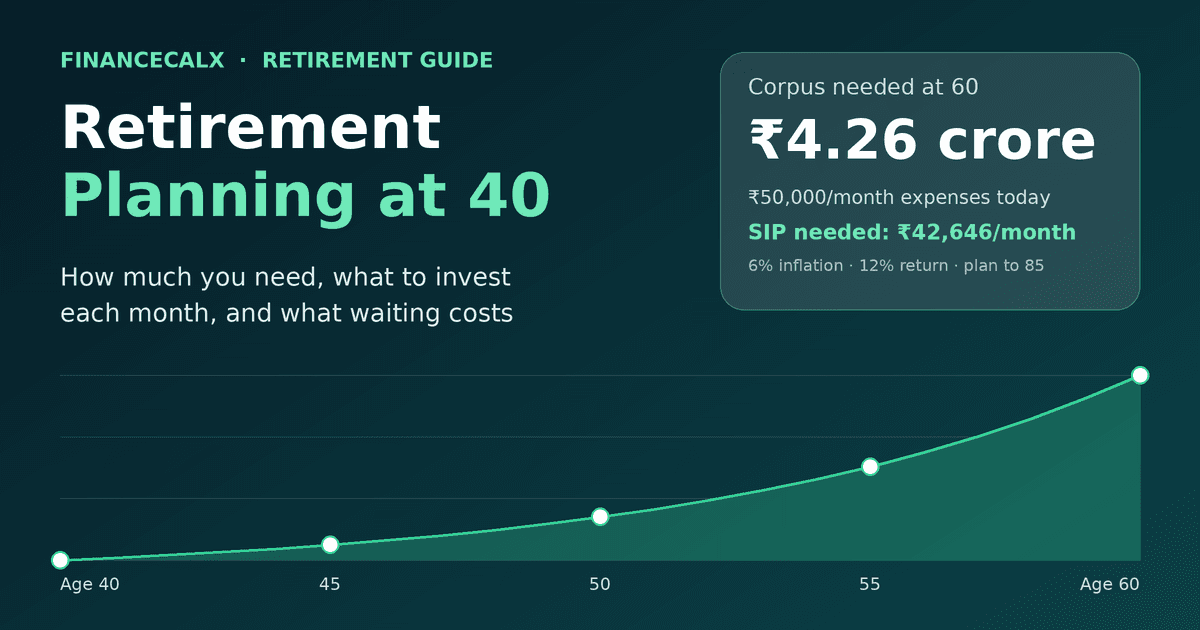
Retirement Planning at 40: A Complete Guide
A 40-year-old spending ₹50,000 a month needs about ₹4.26 crore at 60. Here is the monthly SIP to build it, what waiting five more years costs, and how savings, step-up SIP and retirement age change the number.