How Much SIP Is Needed for ₹2 Crore?
At 12% a year, about ₹20,017 a month for 20 years builds ₹2 crore. Here is the exact SIP amount for every time frame, how step-up SIP lowers it, and what ₹2 crore will really be worth after inflation.
Key takeaways
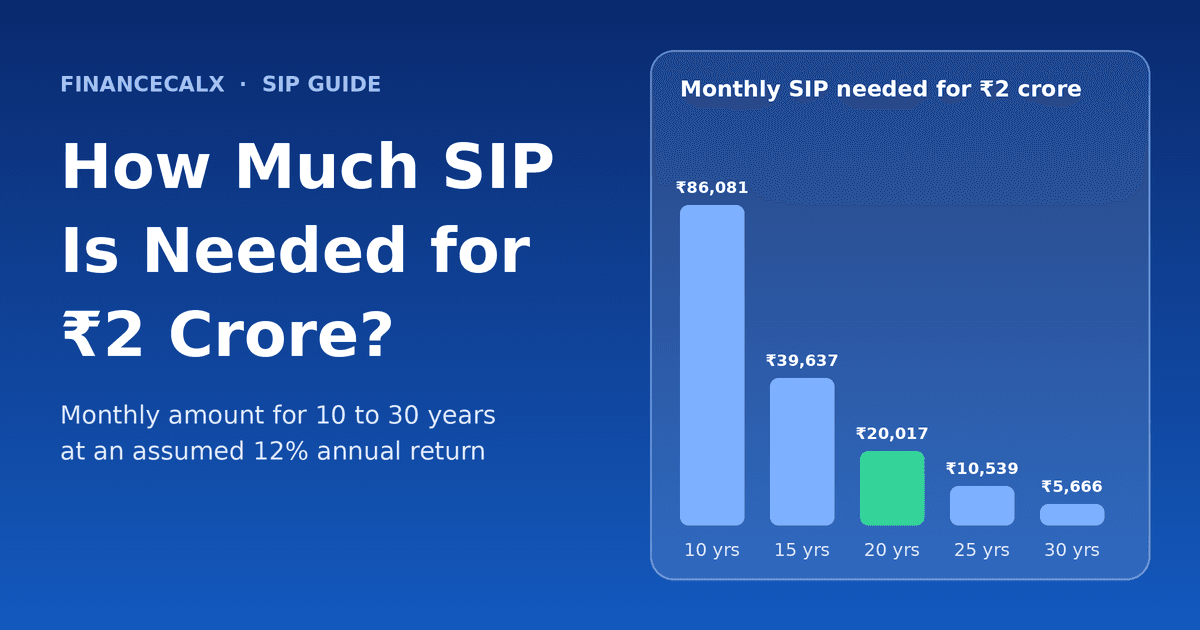
- At an assumed 12% a year, you need about ₹20,017 a month for 20 years to reach ₹2 crore. It is ₹86,081 for 10 years, ₹39,637 for 15 years and ₹10,539 for 25 years.
- Waiting is costly. Moving from a 20-year plan to a 15-year plan almost doubles the monthly amount you need.
- A 10% yearly step-up lets you start a 20-year plan with about ₹10,056 a month instead of ₹20,017.
- Inflation matters. At 6% a year, ₹2 crore in 20 years buys what only about ₹62 lakh buys today.
The short answer
If your SIP earns an average of 12% a year, you need to invest about ₹20,017 a month for 20 years to build ₹2 crore. For a shorter goal, the monthly amount rises quickly: about ₹86,081 for 10 years and ₹39,637 for 15 years. For a longer one, it falls to about ₹10,539 for 25 years.
The right number for you depends on three things: how many years you have, the return you assume, and whether you raise your SIP every year. This guide gives you the exact amount for each case. You can check any figure in our free goal-based SIP calculator.
Monthly SIP needed for ₹2 crore, by time period
Nobody can promise a return, so the table below shows four possible average annual returns. Use 8% if you invest in hybrid or conservative funds, 10–12% for a typical long-term equity plan, and 14% only as an optimistic case.
| Time period | 8% return | 10% return | 12% return | 14% return |
|---|---|---|---|---|
| 10 years | ₹1,08,598 | ₹96,828 | ₹86,081 | ₹76,309 |
| 15 years | ₹57,414 | ₹47,856 | ₹39,637 | ₹32,634 |
| 20 years | ₹33,730 | ₹26,120 | ₹20,017 | ₹15,194 |
| 25 years | ₹20,891 | ₹14,949 | ₹10,539 | ₹7,333 |
| 30 years | ₹13,331 | ₹8,775 | ₹5,666 | ₹3,599 |
Read the table from top to bottom and one thing stands out: time does most of the work. At 12%, extending your plan from 10 years to 20 years cuts the monthly amount from ₹86,081 to ₹20,017. That is less than a quarter, even though you invest for twice as long. A goal of ₹2 crore in 5 years is possible too, but it needs about ₹2.42 lakh a month at 12%, which is out of reach for most people.
Free toolGoal-Based SIP CalculatorEnter ₹2 crore, your time frame and expected return to get the exact monthly SIP for your plan.Open calculator →How much of the ₹2 crore comes from your own money?
The longer you invest, the more your money does the work. This table splits the ₹2 crore into what you put in and what compounding adds, at an assumed 12% return:
| Time period | Monthly SIP | You invest | Growth adds | Share from growth |
|---|---|---|---|---|
| 10 years | ₹86,081 | ₹1.03 crore | ₹96.70 lakh | 48% |
| 15 years | ₹39,637 | ₹71.35 lakh | ₹1.29 crore | 64% |
| 20 years | ₹20,017 | ₹48.04 lakh | ₹1.52 crore | 76% |
| 25 years | ₹10,539 | ₹31.62 lakh | ₹1.68 crore | 84% |
| 30 years | ₹5,666 | ₹20.40 lakh | ₹1.80 crore | 90% |
In a 30-year plan, you put in about ₹20 lakh and growth supplies the other ₹1.80 crore. In a 10-year plan, you put in more than ₹1 crore yourself. This is why starting early feels almost unfair to those who start late.
How long will your current SIP take to reach ₹2 crore?
Maybe you already invest a fixed amount and want to know when you will get there. This table shows the time needed for common SIP amounts:
| Monthly SIP | At 10% return | At 12% return | At 14% return |
|---|---|---|---|
| ₹5,000 | 35 years 6 months | 31 years 1 month | 27 years 9 months |
| ₹10,000 | 28 years 10 months | 25 years 6 months | 22 years 11 months |
| ₹15,000 | 25 years | 22 years 3 months | 20 years 2 months |
| ₹20,000 | 22 years 5 months | 20 years 1 month | 18 years 2 months |
| ₹25,000 | 20 years 5 months | 18 years 4 months | 16 years 9 months |
| ₹30,000 | 18 years 10 months | 17 years | 15 years 7 months |
| ₹50,000 | 14 years 8 months | 13 years 5 months | 12 years 5 months |
A ₹10,000 SIP is a good example. It grows to about ₹99.91 lakh in 20 years at 12%, just short of ₹1 crore, and needs around 25 years and 6 months to reach ₹2 crore. The second crore comes much faster than the first, because a bigger corpus earns bigger returns.
Step-up SIP: start smaller and still get there
Most people earn more every year, so it makes sense to invest more every year. A step-up SIP raises your monthly amount by a fixed percentage each year. It lowers the amount you need to start with, which makes the goal easier to begin.
| Time period | Fixed SIP (no step-up) | 5% yearly step-up | 10% yearly step-up |
|---|---|---|---|
| 10 years | ₹86,081 | ₹71,763 | ₹59,271 |
| 15 years | ₹39,637 | ₹30,624 | ₹23,031 |
| 20 years | ₹20,017 | ₹14,559 | ₹10,056 |
| 25 years | ₹10,539 | ₹7,313 | ₹4,678 |
You can test your own starting amount and step-up in the SIP calculator.
Already have savings? A lump sum shortens the road
If you already have money invested toward this goal, it keeps growing while your SIP builds alongside it. For example, ₹5 lakh invested today at 12% grows to about ₹29.98 lakh in 15 years. That leaves ₹1.70 crore to build, so the 15-year SIP drops from ₹39,637 to about ₹33,696 a month.
To see what a one-time investment can grow to, use the lumpsum calculator. To include existing savings in your target, fill in the current savings field of the goal-based SIP calculator.
Is ₹2 crore enough? The inflation reality check
₹2 crore sounds like a lot today, but prices rise every year. If inflation averages 6%, the same amount of money buys less and less over time. The table shows what your ₹2 crore will feel like, and how much you would need to keep today's buying power:
| Time period | ₹2 crore feels like (today's money) | Corpus needed for ₹2 crore of today's buying power | Monthly SIP needed at 12% |
|---|---|---|---|
| 10 years | ₹1.12 crore | ₹3.58 crore | ₹1,54,158 |
| 15 years | ₹83.45 lakh | ₹4.79 crore | ₹94,993 |
| 20 years | ₹62.36 lakh | ₹6.41 crore | ₹64,197 |
| 25 years | ₹46.60 lakh | ₹8.58 crore | ₹45,234 |
| 30 years | ₹34.82 lakh | ₹11.49 crore | ₹32,542 |
A ₹2 crore target is still a strong goal. It can fund a home down payment, a child's education or part of your retirement. Just make sure the target is set in future rupees, not today's. The inflation calculator turns any of today's costs into their future value.
What can go wrong on the way to ₹2 crore
- Returns are not steady. A 12% average can hide years of 30% gains and years of losses. A bad stretch close to your goal date hurts the most, so move gradually to safer funds in the last few years.
- Inflation changes the target. As shown above, ₹2 crore in the future is worth much less than ₹2 crore today. Review your goal amount every year.
- Taxes reduce what you keep. At the time of writing, gains from equity mutual funds held for more than 12 months are taxed at 12.5% above ₹1.25 lakh of gains in a financial year. Redeeming the whole 20-year plan above at once would mean tax of roughly ₹18–19 lakh, before cess. Spreading withdrawals over several years can help. Always check the latest rules before you redeem.
- Stopping the SIP. Pausing when markets fall means you skip the cheapest units. Automate your SIP and step-up on a fixed date so the plan runs without daily decisions.
- Costs eat returns. A 1% higher fund expense ratio can cost lakhs over 20 years. Compare costs before you pick a fund.
A simple plan to reach ₹2 crore
- Fix your deadline. Choose the year you need the money. This decides everything else.
- Decide if ₹2 crore is in today's or future rupees. If it is in today's money, adjust the goal for inflation first.
- Find your monthly SIP. Use the goal-based SIP calculator with a cautious return such as 10%, not the highest one.
- Start now, even if it is small. Begin with what you can afford and add a 5–10% yearly step-up.
- Add any lump sum. If you have existing savings or a bonus, put it to work with the lumpsum calculator.
- Plan the withdrawal. When you get there, a systematic withdrawal plan can turn the corpus into a monthly income. See how long it lasts in the SWP calculator.
- Review once a year. Check your progress, your income and your goal, then adjust.
Run your own numbers
Your time frame, income and comfort with risk are different from the examples above. The best next step is to try your own figures. All FinanceCalx calculators are free, need no sign-up and run in your browser, so nothing you enter is stored.
Free toolSIP CalculatorTry your own monthly amount, return and step-up, and see the year-by-year growth.Open calculator →Frequently Asked Questions
Calculators used in this guide
SIP Calculator
Estimate the future value of your monthly SIP investments.
CalculateGoal-Based SIP Calculator
Find out how much SIP you need to reach a specific financial goal.
CalculateInflation Calculator
See how inflation affects the future cost and purchasing power of money.
CalculateLumpsum Calculator
Calculate returns on a one-time lumpsum mutual fund investment.
CalculateSWP Calculator
Plan systematic withdrawals from your mutual fund investments.
Calculate